Erwan Jacob
- Major central banks are becoming increasingly focused on the inflationary risks associated with higher energy prices.
- The persistence of the shock matters more than its initial size, particularly if higher costs begin feeding into wages and broader price pressures.
- Markets are reassessing the outlook for interest rates, sovereign yields and safe-haven assets as energy-related inflation risks evolve.
Introduction
The global monetary policy backdrop has shifted materially in recent weeks. The Federal Reserve, European Central Bank and Bank of Japan have all raised policy rates as policymakers respond to persistent inflation pressures, resilient economic activity and renewed uncertainty stemming from the Middle East.
A common thread connects these decisions. Higher energy prices represent an external supply shock that central banks cannot directly reverse. Monetary policy cannot increase oil production or resolve geopolitical disruption. It can, however, seek to prevent an initial increase in energy and transportation costs from becoming embedded in broader prices, wages and inflation expectations.
This distinction is increasingly important for financial markets. The key question is not simply whether oil prices have risen, but how persistent the shock proves to be and whether it generates second round inflation effects. Central banks may initially have viewed the Middle East conflict as relatively short-lived, but the risk of more persistent inflationary effects has since become increasingly important.
Federal Reserve: Inflation remains above target
On 16 September, the Federal Reserve increased the federal funds target range by 25 basis points to 3.75-4.00%. The Federal Open Market Committee (FOMC) described US economic activity as expanding at a solid pace, while noting elevated inflation and increased uncertainty associated in part with geopolitical developments.
The Fed operates under a dual mandate of maximum employment and price stability. The FOMC defines price stability as 2% personal consumption expenditures (PCE) inflation over the longer run.
Recent LSEG data illustrates the balancing act. US headline CPI inflation reached 3.4% year-on-year in August, with prices rising 0.4% month-on-month. Energy was an important contributor: gasoline prices increased 3.9% during August.
The labour market, meanwhile, remains relatively resilient. Non-farm payrolls increased by 162,000 in August, while unemployment was unchanged at 4.1%.
The Fed's September projections envisage 2.3% real GDP growth in 2026, alongside a 4.1% unemployment rate at year end. Median projections put PCE inflation at 3.7% in 2026 and core PCE inflation at 3.4%, both well above the longer run 2% objective.
Figure 1: US interest rate and YoY CPI inflation
ECB: Energy shock meets modest growth
The ECB increased its three key policy rates by 25 basis points on 10 September. Its deposit facility rate consequently rose to 2.50%, with the main refinancing and marginal lending rates rising to 2.65% and 2.90%, respectively. The ECB explicitly cited inflation pressures associated with the Middle East conflict.
Unlike the Fed, the ECB has a primary mandate of price stability, which it defines as 2% inflation over the medium term.
Euro area inflation increased to 3.2% in August from 2.9% in July. Energy contributed 1.29 percentage points to the annual inflation rate, demonstrating the extent to which external energy developments are influencing the regional price environment.
According to the ECB, headline inflation is projected to average 3.0% this year, before declining to 2.5% in 2027 and 2.1% in 2028.This leaves the ECB confronting an uncomfortable policy mix: relatively modest growth alongside inflation materially above target.
Figure 2: Eurozone interest rate and YoY CPI inflation
Japan: Another step towards policy normalisation
Japan provides a different starting point but faces a similar external challenge. The Bank of Japan raised its overnight policy rate to around 1.25% on 18 September, continuing the gradual withdrawal of monetary accommodation.
The BoJ conducts monetary policy with the objective of achieving price stability around its 2% target. Its July outlook projected 0.6% real GDP growth in fiscal 2026 and a 2.5% increase in CPI excluding fresh food. The Bank also highlighted higher crude prices associated with the Middle East as a downside risk to economic activity and an upside influence on inflation.
Japan's unemployment rate was just 2.4% in July, pointing to a comparatively tight labour market.
Japan's dependence on imported energy makes the interaction between crude prices, the yen and domestic inflation particularly relevant. Higher imported energy costs can simultaneously weaken real activity and raise consumer prices, complicating the calibration of monetary policy.
Figure 3: Japan interest rate and YoY CPI inflation
Macro fundamentals and the yield curve
The changing macro environment also has important implications for sovereign yield curves. The distinction between the front and long end matters. Short-dated yields are closely linked to expectations for central-bank policy, while longer maturities incorporate a broader set of macro fundamentals, including expected nominal growth, inflation uncertainty, government borrowing requirements.
The shape of the curve therefore increasingly reflects the interaction between monetary policy and the underlying macro fundamentals rather than the policy rate alone.
Gold: Caught between higher yields and geopolitical uncertainty
Gold sits at the intersection of these competing forces.
Higher interest rates and real yields generally represent a headwind because gold produces no coupon or income. As yields on government securities rise, the opportunity cost of holding non-yielding bullion increases. A stronger US dollar associated with higher US rates can add further pressure.
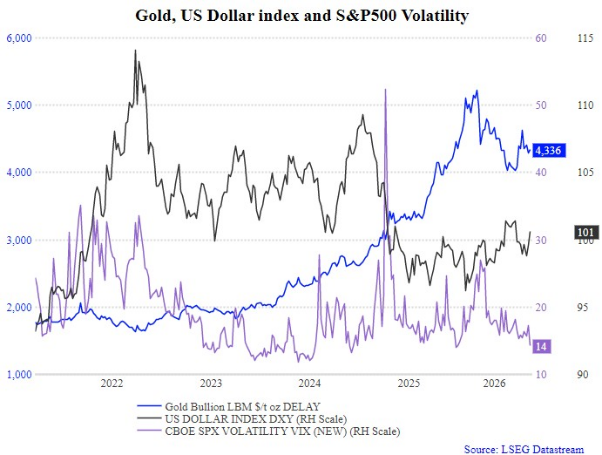
That mechanism has recently been visible in prices. Gold futures settled around US$4,346 per ounce on 21 September, declining as higher US rates and yields weighed on the metal. However, the relationship is not one-dimensional. Geopolitical uncertainty, concerns about persistent inflation and demand for perceived safe-haven assets can provide offsetting support.
Figure 4: Gold, US dollar index and S&P500 volatility
Source: LSEG Datastream.
Past performance is not a guide to future returns. Please see the end for important legal disclosures.
| Date | Gold Bullion (LBM $/t oz, delayed) | US Dollar Index (DXY) | CBOE S&P 500 Volatility Index (VIX) | Key observation |
|---|---|---|---|---|
| 2021 | ~1,800 | ~95 | ~15-35 | Gold relatively stable, dollar strengthens, volatility elevated. |
| 2022 | ~1,650-2,000 | Peaks near 113 | Frequently above 20, spikes above 30 | Strong US dollar and increased market volatility. |
| 2023 | ~1,900-2,000 | Range-bound around 100-106 | Mostly 12-20 | Volatility moderates while gold remains stable. |
| 2024 | ~2,000-2,800 | Rises then falls from ~108 to ~101 | Significant spikes, including a peak above 50 | Gold begins a strong upward trend despite volatility. |
| 2025 | ~3,300-5,200 | Generally 98-101 | Mostly 14-20 with occasional spikes | Gold rallies sharply while the dollar weakens. |
| 2026 | ~4,300-4,900 | Around 101 | Around 14 | Gold remains elevated, volatility subdued, dollar stable. |
From temporary shock to persistent inflation risk
The duration of the geopolitical disruption is arguably the critical variable for markets.
Some market moves have reflected expectations that Middle East-related disruptions could prove relatively contained. That assumption matters because a short-lived oil shock has very different macroeconomic consequences from a persistent one.
If elevated energy prices persist, their impact can extend beyond headline inflation. Oil feeds into transportation, aviation, manufacturing, chemicals, agriculture and logistics, while disruption to shipping can increase freight and insurance costs. Businesses may absorb some of those increases, but persistent cost pressure raises the probability of pass-through to consumer prices and wages.
This is where an exogenous supply shock becomes relevant for monetary policy. Central banks cannot eliminate the original supply constraint, and excessive tightening in response to a purely temporary shock could unnecessarily weaken activity. But policymakers must also consider the risk that persistent increases in energy and other input costs affect inflation expectations, wage setting and broader price formation.
The recent tightening by the Fed, ECB and BoJ therefore reflects a broader change in the macro environment. The central issue is increasingly persistence rather than simply the initial size of the energy shock. The evolution of oil prices, underlying inflation, labour markets and inflation expectations will help determine whether the current tightening cycle remains relatively contained or requires policy to remain restrictive for longer.

Legal Disclaimer
Republication or redistribution of LSE Group content is prohibited without our prior written consent.
The content of this publication is for informational purposes only and has no legal effect, does not form part of any contract, does not, and does not seek to constitute advice of any nature and no reliance should be placed upon statements contained herein. Whilst reasonable efforts have been taken to ensure that the contents of this publication are accurate and reliable, LSE Group does not guarantee that this document is free from errors or omissions; therefore, you may not rely upon the content of this document under any circumstances and you should seek your own independent legal, investment, tax and other advice. Neither We nor our affiliates shall be liable for any errors, inaccuracies or delays in the publication or any other content, or for any actions taken by you in reliance thereon.
Copyright © 2026 London Stock Exchange Group. All rights reserved.
The content of this publication is provided by London Stock Exchange Group plc, its applicable group undertakings and/or its affiliates or licensors (the “LSE Group” or “We”) exclusively.
Neither We nor our affiliates guarantee the accuracy of or endorse the views or opinions given by any third party content provider, advertiser, sponsor or other user. We may link to, reference, or promote websites, applications and/or services from third parties. You agree that We are not responsible for, and do not control such non-LSE Group websites, applications or services.
The content of this publication is for informational purposes only. All information and data contained in this publication is obtained by LSE Group from sources believed by it to be accurate and reliable. Because of the possibility of human and mechanical error as well as other factors, however, such information and data are provided "as is" without warranty of any kind. You understand and agree that this publication does not, and does not seek to, constitute advice of any nature. You may not rely upon the content of this document under any circumstances and should seek your own independent legal, tax or investment advice or opinion regarding the suitability, value or profitability of any particular security, portfolio or investment strategy. Neither We nor our affiliates shall be liable for any errors, inaccuracies or delays in the publication or any other content, or for any actions taken by you in reliance thereon. You expressly agree that your use of the publication and its content is at your sole risk.
To the fullest extent permitted by applicable law, LSE Group, expressly disclaims any representation or warranties, express or implied, including, without limitation, any representations or warranties of performance, merchantability, fitness for a particular purpose, accuracy, completeness, reliability and non-infringement. LSE Group, its subsidiaries, its affiliates and their respective shareholders, directors, officers employees, agents, advertisers, content providers and licensors (collectively referred to as the “LSE Group Parties”) disclaim all responsibility for any loss, liability or damage of any kind resulting from or related to access, use or the unavailability of the publication (or any part of it); and none of the LSE Group Parties will be liable (jointly or severally) to you for any direct, indirect, consequential, special, incidental, punitive or exemplary damages, howsoever arising, even if any member of the LSE Group Parties are advised in advance of the possibility of such damages or could have foreseen any such damages arising or resulting from the use of, or inability to use, the information contained in the publication. For the avoidance of doubt, the LSE Group Parties shall have no liability for any losses, claims, demands, actions, proceedings, damages, costs or expenses arising out of, or in any way connected with, the information contained in this document.
LSE Group is the owner of various intellectual property rights ("IPR”), including but not limited to, numerous trademarks that are used to identify, advertise, and promote LSE Group products, services and activities. Nothing contained herein should be construed as granting any licence or right to use any of the trademarks or any other LSE Group IPR for any purpose whatsoever without the written permission or applicable licence terms.